Hedge Wealth Capital
DSCR Loan Program

DSCR Loans for Investment Property 

Qualify on what the property earns, not on your pay stubs. Our 30-year fixed DSCR loan uses rental cash flow to approve purchases, rate-and-term refinances and cash-out refinances, with no tax returns required.

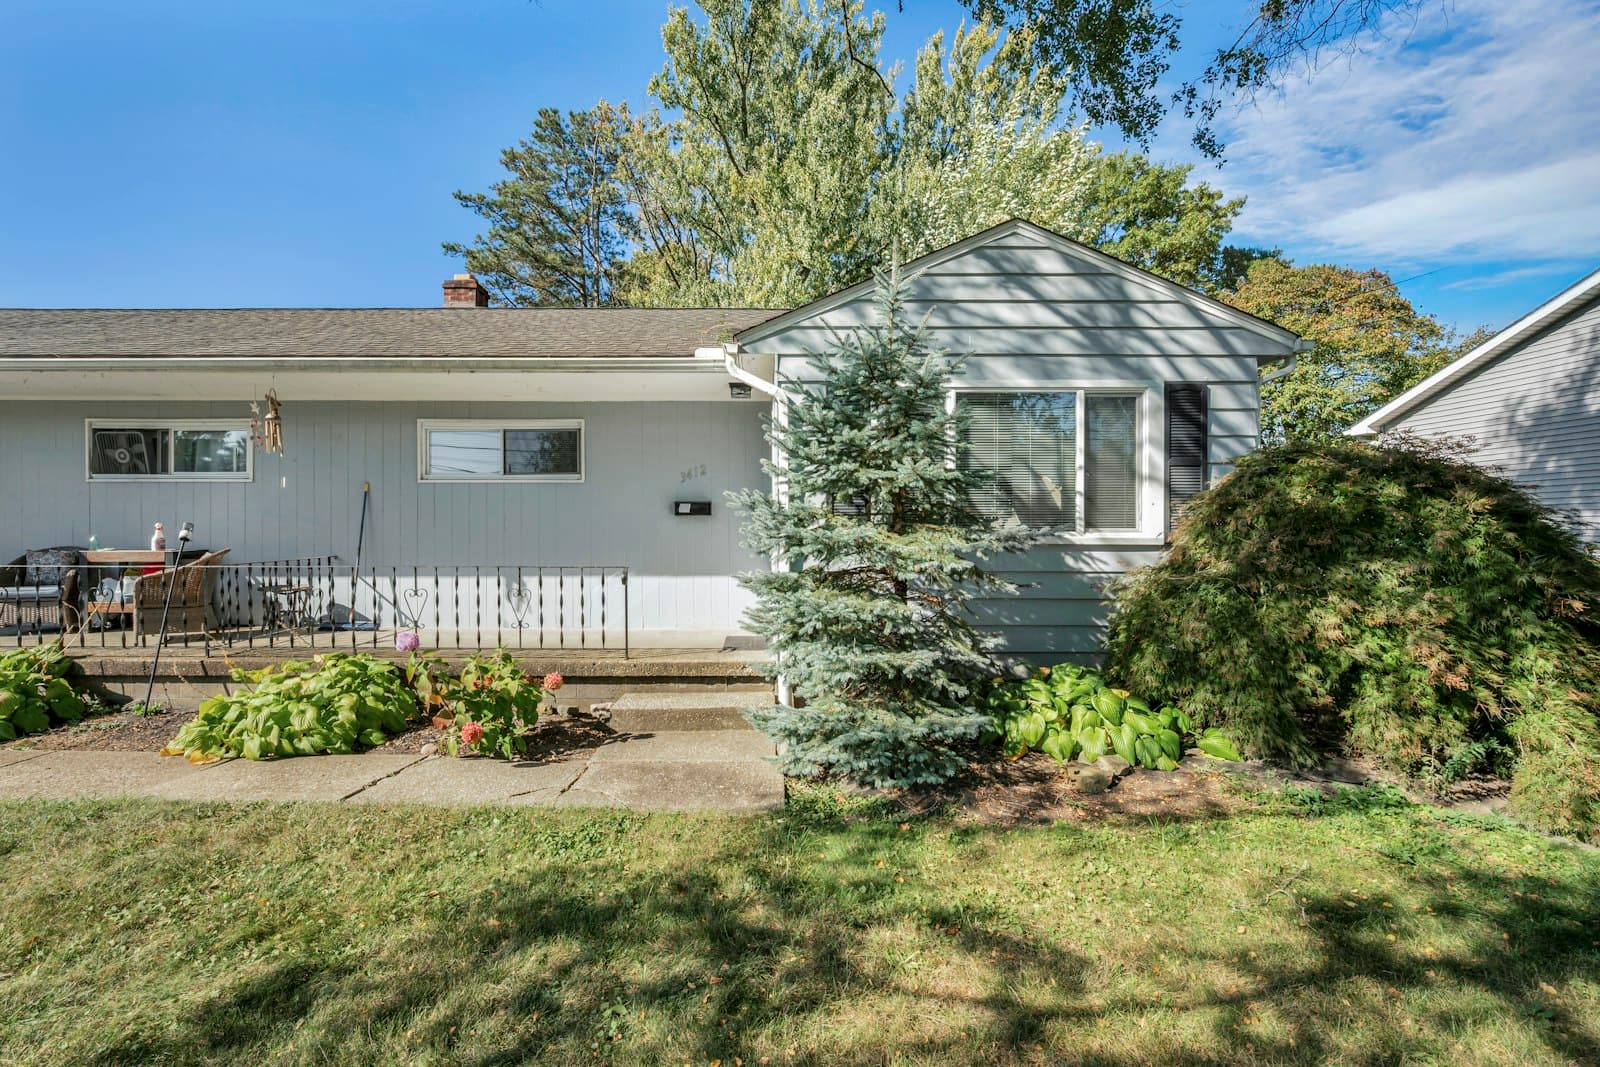
Single-family rental home financed with a 30-year DSCR loan

Program snapshot

Max LTV on purchase
80%
Max LTV on purchase
Fixed rate, no call
30-YR
Fixed rate, no call
FICO score
680+
FICO score
Min. property value
$100K
Min. property value

What Is a DSCR Loan?

A debt service coverage ratio (DSCR) loan is approved on the cash flow of the rental itself. We compare the property's rental income with its monthly debt payment. If the rent covers the payment, the property can qualify, regardless of what your personal tax return says.

That makes DSCR financing the natural long-term home for investors who are self-employed, own several properties, or simply do not want to document personal income for every purchase. It is also the most common exit for hard money loans once a renovation is finished.
Well-kept rental property with a porch and lawn
DSCR Calculator

Does the Rent Cover the Payment?

$2,400
$1,850

1.30

Rent covers the payment

Illustrative only. DSCR = monthly rent ÷ monthly principal, interest, taxes, insurance and association dues (PITIA). Qualification, rate and leverage depend on the full loan review.
DSCR Program Highlights

Built for buy-and-hold investors who want predictable, long-term debt.

Up to 80% LTV

80% on purchases and rate-and-term refinances, and up to 75% on cash-out refinances.

680+ FICO

Minimum score of 680, with exceptions considered down to 660. Your score helps set your rate.

Single-family to 10 units

Single-family and 2–10 unit residential rentals, including short-term rentals.

LLCs and individuals

Close in your own name or your entity's, with cash-flow based approval and no DTI.

Flexible prepayment

Declining prepayment structures such as 3-2-1 or 5-4-3-2-1, with zero-penalty options available.

15-year option

Prefer to pay down faster? Ask about our 15-year term with 15-year amortization.

Step by Step

Documents for a DSCR Loan 

1

One-page application

A short application covering you, the property and the loan you want.

2

Lease and insurance

An executed lease showing rental income, plus proof of property insurance.

3

Settlement statement

The purchase settlement statement for the property being financed.

4

ID, bank statements and entity docs

Valid ID, two months of bank statements, and entity documents with a W-9 if borrowing through an LLC.

Compare

DSCR Loan vs. Conventional Mortgage 

Conventional loans can carry lower rates for those who qualify, but they are hard to scale.

Qualifies on

HWC DSCR loan: Property cash flow and credit

Conventional loan: Personal income and DTI

Paperwork

HWC DSCR loan: Low-doc: no tax returns or pay stubs

Conventional loan: Full income documentation

Borrower

HWC DSCR loan: LLCs and individuals

Conventional loan: Usually individuals only

Scaling

HWC DSCR loan: From one rental to a portfolio

Conventional loan: Agency limits on financed properties

FAQ

Frequently Asked Questions 

Still have a question?

Talk to our team about your property and timeline.

1-800-674-3804

The minimum FICO score is 680, with exceptions considered as low as 660. Your credit score helps determine the rate you are quoted.

Talk With HWC 

Have a property under contract or a project you are evaluating? Tell us where things stand and what financing questions you need to resolve.