Hedge Wealth Capital
Hard Money Fix & Flip Loans

Hard Money Loans for Flipping Houses 

Buy the house and fund the renovation with one short-term loan. Hedge Wealth Capital lends up to 100% of the purchase price and 100% of the rehab budget, so more of your cash stays free for the next deal.

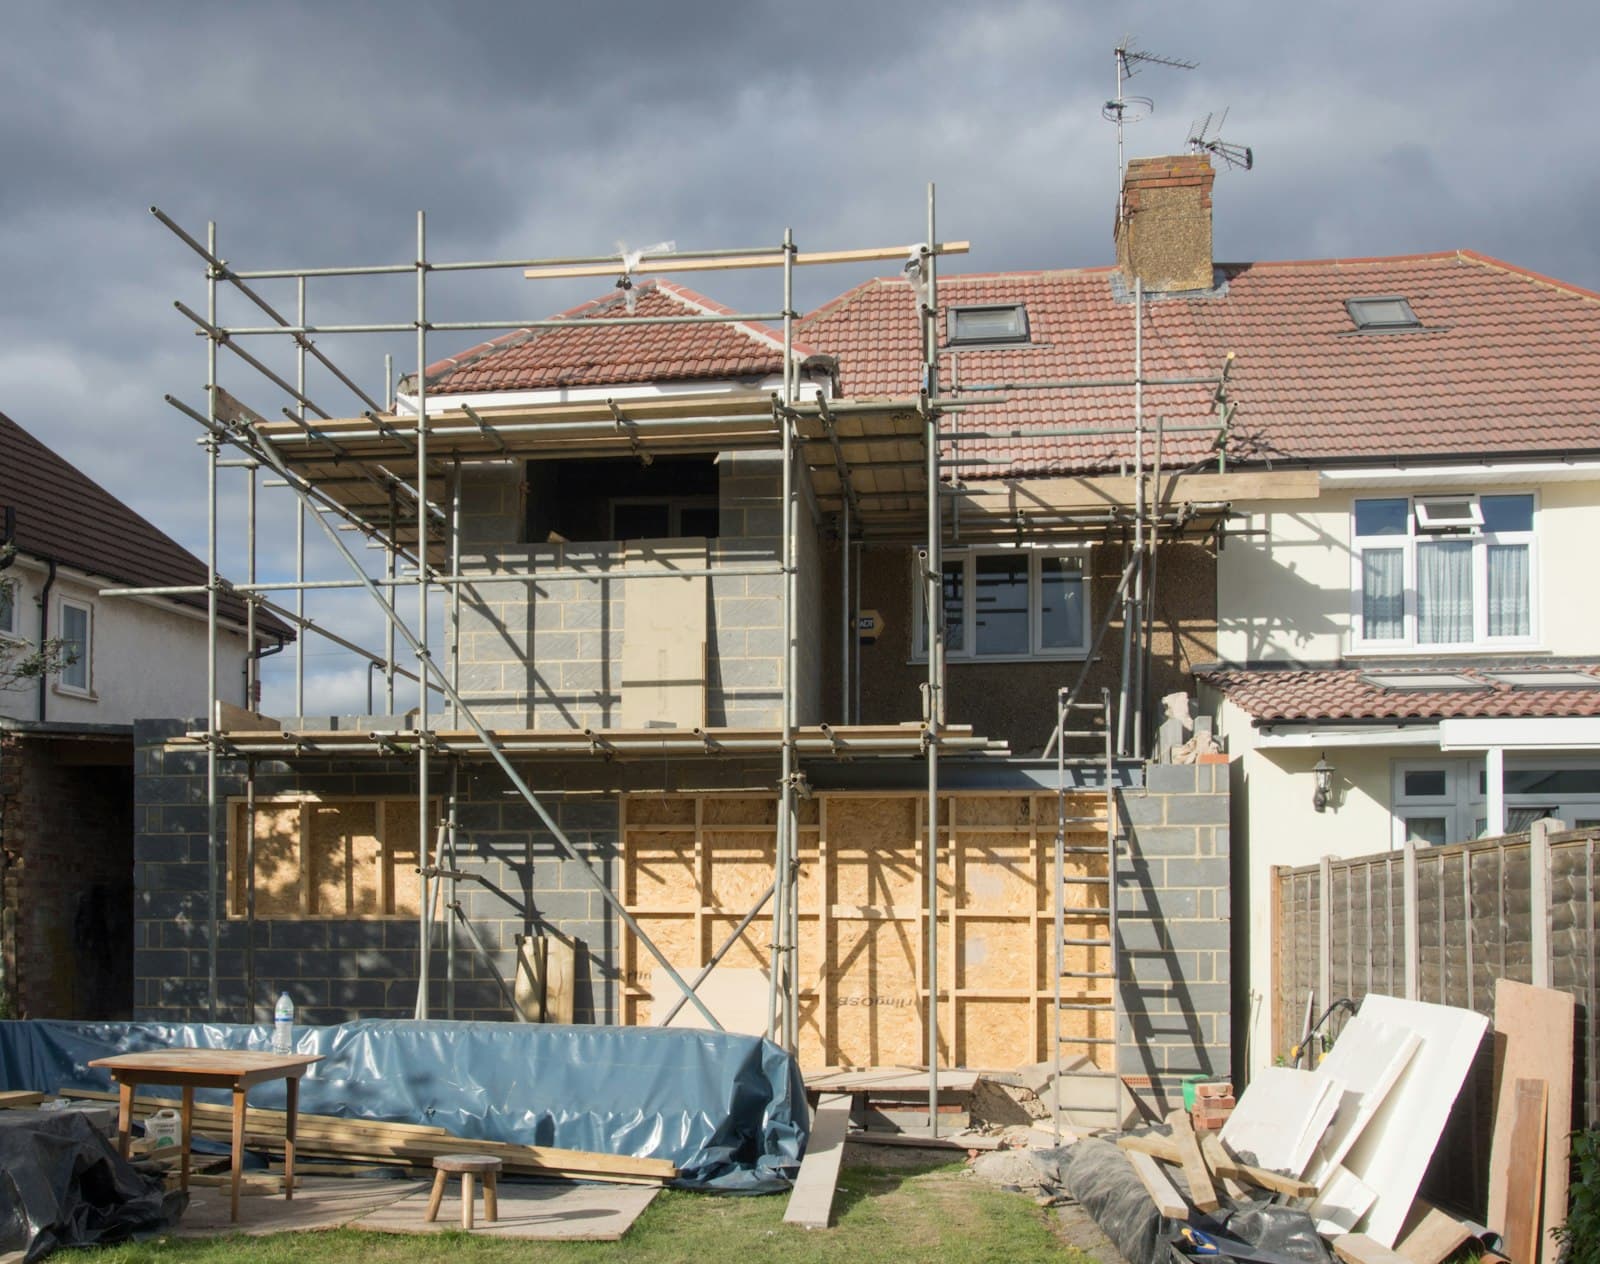
House under renovation with scaffolding, financed with a hard money loan

Program snapshot

Of purchase price
100%
Of purchase price
Of rehab budget
100%
Of rehab budget
Month interest-only terms
6–12
Month interest-only terms
Prepayment penalty
$0
Prepayment penalty

How a Hard Money Loan to Flip Houses Works

A hard money loan is short-term, asset-based financing secured by the property you are buying. Instead of qualifying you on W-2s and debt-to-income ratios, we look at the deal itself: the purchase price, the scope of work, and what the home should be worth once the work is done.

Your loan amount is sized on both total project cost (loan-to-cost) and the after-repair value. Fund up to 100% of acquisition and rehab, subject to an ARV cap that keeps every project sensibly leveraged. If ARV is the number that drives your deal, our ARV loans page explains how after-repair value is measured.

Payments are interest-only for a 6 to 12 month term, with the balance due when you sell or refinance. There is no prepayment penalty, so paying the loan off the week the house sells costs you nothing extra.
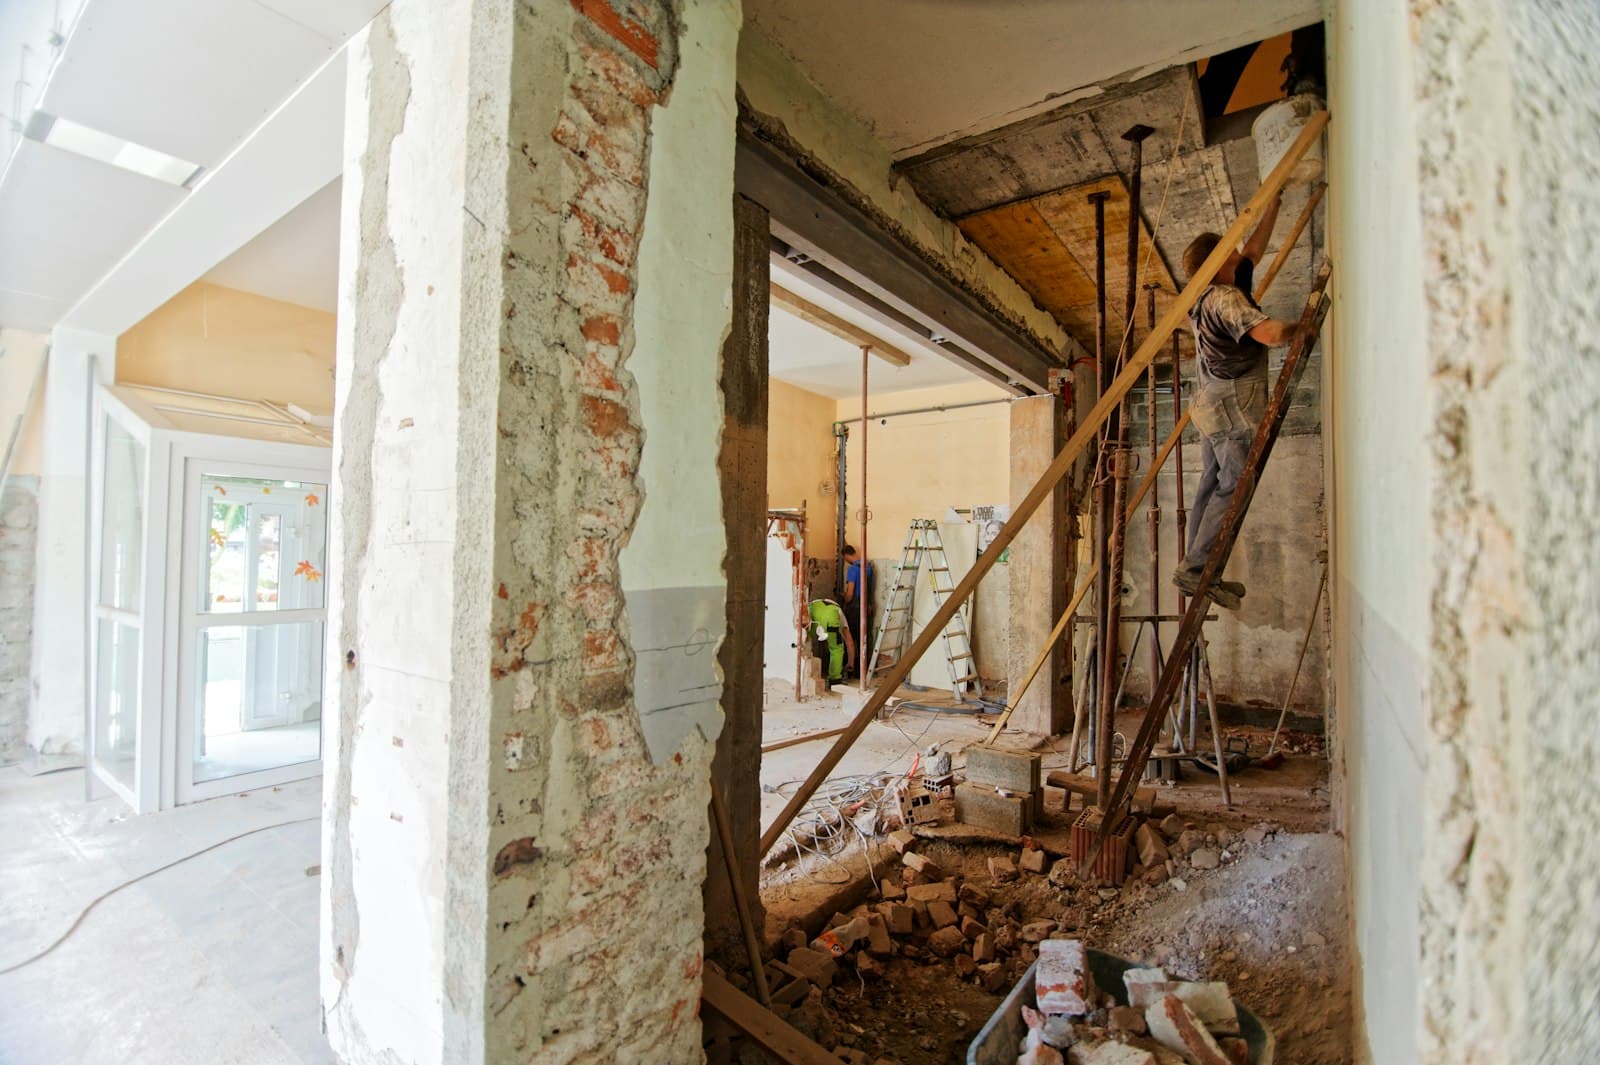
Interior gut renovation in progress on a fix and flip property
Interactive Estimate

How Much Could You Borrow?

$220,000
$60,000
$420,000
$280,000
Project cost
$294,000
ARV cap (70%)
$280,000
Estimated loan

Estimated loan

$280,000

Gap above the loan

$0

Illustrative only. Uses up to 100% of purchase and rehab with a 70% ARV cap, and excludes closing costs, reserves and interest, which you pay separately. Your actual loan amount and ARV cap are set by underwriting and final loan terms.
Get Pre-Approved Before You Find the Deal

Speed wins deals. With our Investor Line of Credit you can become an approved borrower before you have a property under contract, so financing is already in place when the right house appears.

No deal required

Apply once, then shop with confidence. We provide proof of funds every 60 days or whenever you ask.

In-house underwriting

Pre-approved borrowers can skip the third-party appraisal; we review the deal ourselves and can fund in as little as 48 hours.

Cash reserves

We recommend at least $30,000 in available reserves to qualify for a line of credit and move quickly.

No upfront points option

Ask about structures with no upfront origination points to keep more cash in the project.

Properties and Borrowers We Finance

We primarily finance single-family attached and detached homes, plus small multifamily rentals that need work before they can be sold or refinanced. Loans are business-purpose only, so we do not lend on owner-occupied primary residences.

Perfect credit is not required. We look at the reasons behind any credit challenges, although a bankruptcy, foreclosure, short sale, lien or judgment in the last 24 months may stop an approval for now. Planning to keep the house as a rental? Exit straight into a long-term DSCR loan once the renovation is complete.

Step by Step

From Pre-Approval to Payoff 

1

Get pre-approved

Share a recent bank statement, a personal financial statement and two years of tax returns. Your tax-return bottom line is not a qualifying factor.

2

Lock up the property

Send the contract, purchase price and a line-item scope of work for the renovation.

3

Close and start work

We fund the purchase at closing and hold the rehab budget for draws as work is completed.

4

Sell or refinance

Pay off the loan with no prepayment penalty, then repeat on the next project.

Compare

Hard Money vs. a HELOC for Your Flip 

A home equity line can work, but it puts your own house on the line if a project runs long.

Collateral

HWC hard money loan: The investment property

HELOC on your home: Your primary residence

Rehab funding

HWC hard money loan: Up to 100% of the budget

HELOC on your home: Limited to your available line

Credit impact

HWC hard money loan: Lines are not reported under normal circumstances

HELOC on your home: Maxing the line can lower your score

Approval basis

HWC hard money loan: The deal and your experience

HELOC on your home: Personal income and DTI

FAQ

Frequently Asked Questions 

Still have a question?

Talk to our team about your property and timeline.

1-800-674-3804

Hedge Wealth Capital lends up to 100% of the purchase price and up to 100% of the rehab budget, subject to an after-repair value cap. You cover closing costs and any expenses outside the approved budget.

Talk With HWC 

Have a property under contract or a project you are evaluating? Tell us where things stand and what financing questions you need to resolve.